Short answer: For most people, two to four credit cards is the sweet spot. That’s enough to build strong credit, keep your utilization low, and earn rewards without losing track of payments. The average American actively uses about 3.7 cards, and people with excellent credit scores tend to have more open accounts, not fewer. But the right number for you depends on where you are: one card is correct when you’re starting out, while a points maximizer can responsibly run five or more. Here’s the number for your exact situation, and the score math behind it.
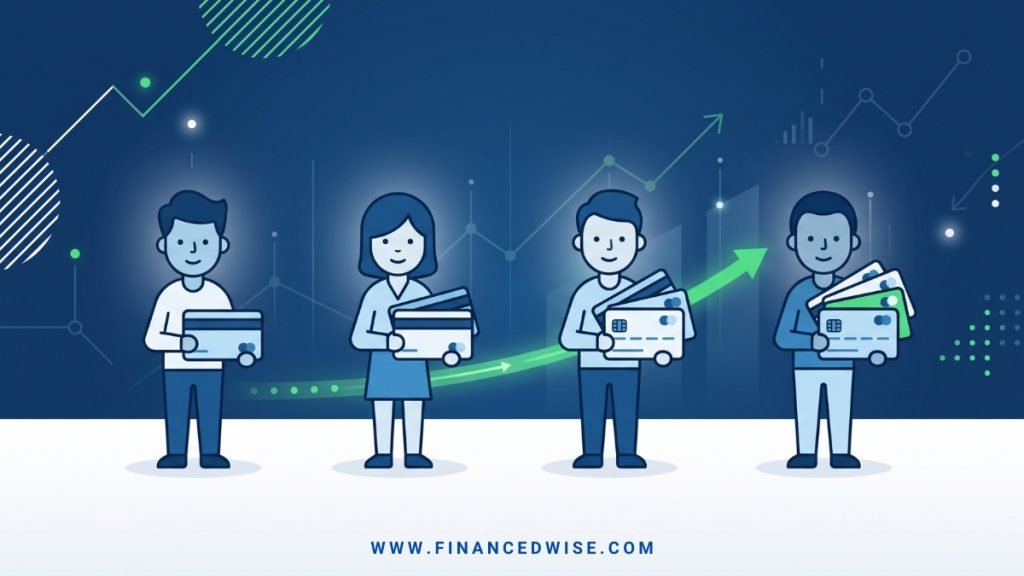
The quick answer by situation
| Your situation | Cards to have | Why |
|---|---|---|
| Building credit from zero | 1 (secured or starter card) | One on-time payment history is all you need to start. More applications now just add denials |
| Student | 1, maybe 2 | One student card used lightly and paid in full builds history while you learn the habit |
| Building toward good credit (score in the 600s) | 2 to 3 | A second card lowers utilization and adds payment history without overwhelming you |
| Established, simple life | 2 to 3 | One daily rewards card, one backup on a different network, optionally one for a specific category |
| Rewards maximizer | 4 to 6+ | Category cards (groceries, travel, gas) plus a flat-rate card, if and only if you never carry a balance |
| Rebuilding after problems | 1 to 2 | Focus on perfect payments on what you have. New applications can wait |
| Recently bankrupt or in active debt payoff | The ones you have, used minimally | Adding cards while paying down debt usually makes both problems worse |
Notice what’s missing from that table: zero. Having no credit card at all is the one option that actively works against you in the US system, because with no revolving accounts you generate no payment history, and payment history is the single biggest part of your score.
What the data says is “normal”
According to Experian, Americans hold an average of 7.1 credit cards but actively use only about 3.7 of them, a number that has actually declined about 10% over the past decade. Roughly 90% of consumers have at least one card, about half have at least two, and 13% have five or more. And here’s the pattern that matters most for this question: higher credit scores correlate with more open accounts, not fewer. People with 800+ scores usually got there with several cards and years of perfect payments, not with one card and caution.
So if you have three or four cards, you are completely normal. The problem is never the count by itself. It’s whether the count matches your discipline.
How the number of cards actually affects your credit score
This is the part most articles wave past, so let’s do the actual mechanics. Your FICO score has five ingredients, and card count touches every one of them:

| Score factor | Weight | More cards helps or hurts? |
|---|---|---|
| Payment history | 35% | Helps, if every card is paid on time. Hurts badly if even one slips |
| Credit utilization | 30% | Helps. More total limit with the same spending means a lower utilization percentage |
| Length of credit history | 15% | Hurts short-term. Each new card lowers your average account age |
| New credit (inquiries) | 10% | Hurts short-term. Each application is a hard inquiry, typically a small temporary dip |
| Credit mix | 10% | Slightly helps to have revolving accounts alongside any loans |
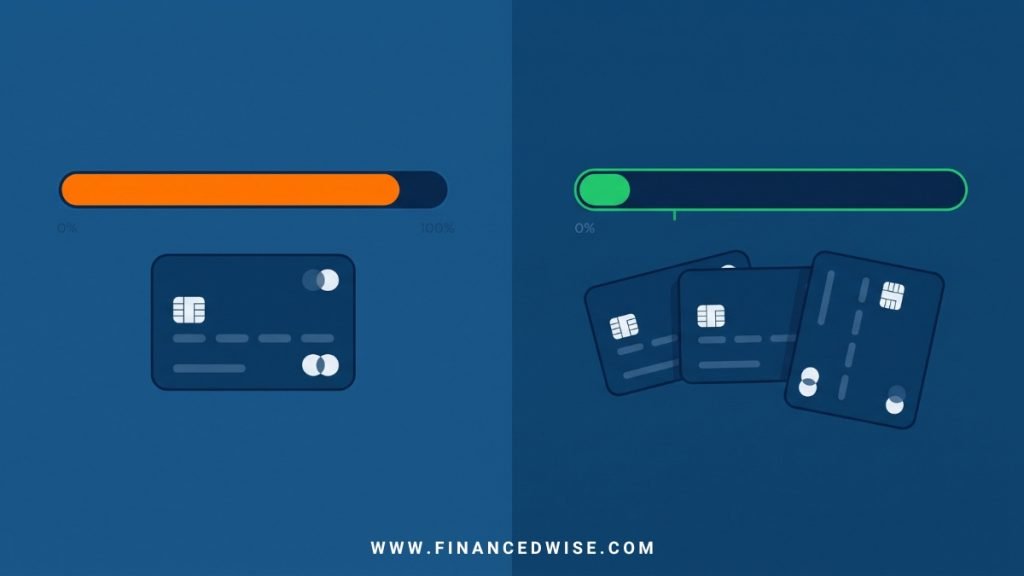
Read that table and the strategy writes itself. Utilization is the reason more cards can raise your score: if you spend $1,000 a month on a single card with a $2,000 limit, you’re at 50% utilization, which drags your score. Spread the same spending across three cards with $6,000 of combined limits and you’re under 17%. Same spending, same person, better score. Aim to keep overall utilization under 30%, and under 10% if you’re optimizing.
The counterweights are account age and inquiries, which is why the answer is “add cards slowly,” not “add cards.” A good rule: no more than one new card every 6 to 12 months, and pause applications entirely for the year before a mortgage or car loan, because lenders look at recent inquiries.
One more real-world rule worth knowing if you’re on the maximizer path: some issuers limit approvals based on how many cards you’ve opened recently across all banks (the best-known example is Chase’s unwritten 5/24 rule, which generally declines applicants who’ve opened five or more cards in the past 24 months). Even card issuers think there’s such a thing as too fast.
Signs you’re ready for another card
- You’ve paid every bill on time for at least six months
- You pay your statement balance in full, not just the minimum
- Your utilization regularly sits above 30% even though you pay in full
- You have a specific reason: a category you spend heavily in, a backup network (Visa plus Mastercard, for example), or a genuinely valuable signup offer
- You’d still comfortably track every due date with one more account
Signs you already have too many
- You’ve missed a payment, or come close, because you forgot a card existed
- You’re carrying balances on multiple cards and paying interest (average APRs are around 21% in 2026, which outruns any reward ever printed)
- You’ve opened cards just for signup bonuses and now pay annual fees on cards you never use
- You feel tempted to spend more because unused limits are sitting there
- Checking your accounts feels like a part-time job
If that second list sounds familiar, the fix is usually not closing cards, which can raise your utilization and shorten your history. Stop using the extras, set autopay minimums as a safety net on everything, and put your spending on one or two cards until the system feels manageable again.
What about business credit cards?
If you run a business or side income, business cards mostly live outside this count. Most business card issuers don’t report routine activity to your personal credit reports (though the application usually involves a personal credit check and a personal guarantee). One or two business cards to separate business spending from personal is good hygiene for bookkeeping and taxes, and for most small operators that’s plenty.
A related post: Which Item is a Benefit of Using the Travel Card
The bottom line
Two to four cards, added slowly, paid in full, every month. That configuration builds an excellent score, earns real rewards, and stays easy to manage. The count matters far less than the two behaviors underneath it: 100% on-time payments and utilization kept low. Get those right and almost any reasonable number of cards works for you. Get them wrong and even one card is too many.
How many credit cards should I have to build credit?
Start with one. A single card, used for small purchases and paid in full every month, builds payment history efficiently. After 6 to 12 months of perfect payments, a second card helps by lowering your utilization and adding another positive account. You don’t need more than two or three to reach a good score.
How many credit cards should I have for a good credit score?
There’s no required number, but two to four is where the math works best for most people: enough combined limit to keep utilization low, few enough to never miss a payment. FICO’s high achievers typically have multiple long-held accounts with spotless payment records.
How many credit cards is too many?
Whatever number you can’t manage perfectly. Practically, warning signs are missed payments, interest charges on multiple cards, and annual fees on cards you don’t use. There’s no score penalty for holding many cards responsibly, but opening many quickly hurts through inquiries and a lower average account age.
Does having multiple credit cards hurt your credit score?
credit scoreNot by itself. Multiple cards usually help by increasing your total limit and lowering utilization. The damage comes from the behaviors that sometimes ride along: applying for several cards in a short window, missing payments across accounts, or running up balances because more credit is available.
Should I close credit cards I don’t use?
Usually no. Closing a card removes its limit from your utilization math and eventually its age from your history, both of which can lower your score. Keep no-fee cards open with a small recurring charge on autopay. Cards with annual fees you’re not getting value from are the exception; downgrade them to a no-fee version where the issuer allows it, or close them if not.
How many credit cards does the average American have?
Americans hold about 7 cards on average but actively use around 3.7, according to Experian data. Half of consumers have at least two cards, and 13% have five or more.
This article is for general education, not personalized financial advice. Credit decisions depend on your full situation, so consider talking to a nonprofit credit counselor or financial advisor before major changes, and check your own credit reports free at annualcreditreport.com.